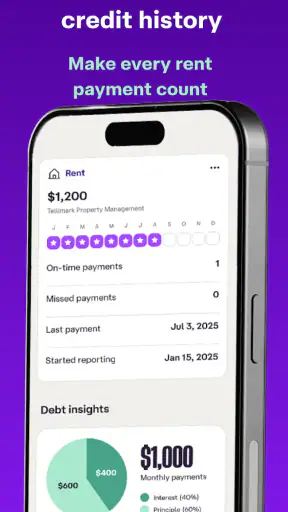
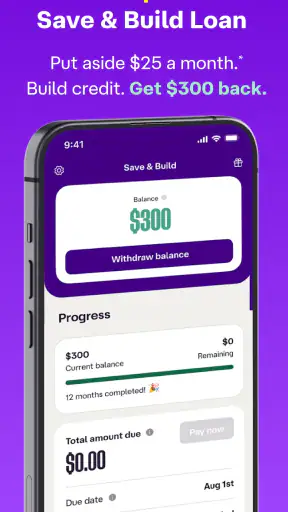
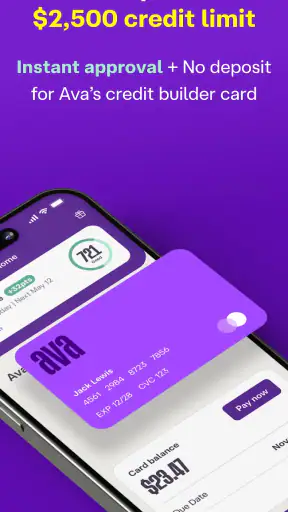
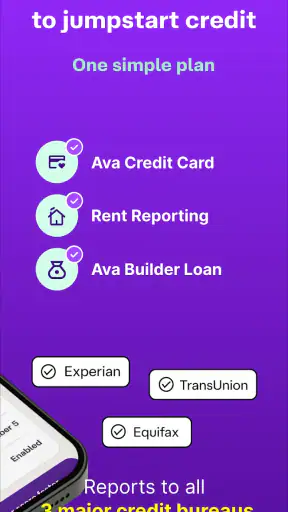
I approached Ava Finance as a practical credit-building app rather than as a complete replacement for a bank, budgeting tool, or financial adviser. That distinction matters. Its focus is narrow and useful: helping people work on their credit profile through a mobile experience, with the promise of making the process feel faster and easier to manage. In my experience, that makes it most interesting for someone who wants a guided starting point, not for someone expecting a full personal-finance dashboard.
The app is listed as free, which removes the biggest barrier to trying it. Free access does not automatically mean that every financial product, optional service, or outcome connected with the app has no cost, so I would still read each screen carefully before accepting anything. The important value judgment is therefore not “is the download free?” alone, but whether the credit-building path fits your situation and whether you are comfortable reviewing the terms attached to the choices presented inside the app.
How Ava Finance fits into everyday credit building
Ava Finance, Inc. is the developer behind this finance app. It is available for Everyone, runs on Android with a minimum operating system of 9, and its current version is 5.1.6626. Those details make it reasonably accessible for people using an older but still supported Android phone. I also like that the product is clearly positioned around credit rather than trying to disguise itself as a general-purpose money app.
The public response is encouraging: the app holds a 4.7 average from around 17 thousand ratings and has passed half a million installs. That does not guarantee that it will suit every financial profile, but it suggests that the basic experience has worked for a substantial group of users. I treat those numbers as a signal to investigate further, not as proof that the app can improve everyone’s credit in the same way.
Credit building is often frustrating because progress depends on habits, reporting, account history, and time. A mobile app can make the routine easier to follow, but it cannot turn responsible borrowing into an instant result. The “build credit fast” positioning is appealing, yet I would interpret it carefully. Fast should mean a simpler route to getting started and staying organized, not a guaranteed score change on a personal timetable.
What the free download is actually worth
The free price is a genuine advantage for someone who is still deciding whether a credit-building service belongs in their routine. You can begin by examining the experience without paying simply to install it. That is more approachable than committing immediately to a traditional paid financial service, especially when you are trying to repair or establish credit and want to limit unnecessary expenses.
Still, free access should not be confused with free credit. Financial apps can present choices whose costs, eligibility requirements, repayment expectations, or reporting details need careful attention. I would never approve an offer while rushing through the setup. I would look for the total obligation, the timing of any payments, and the exact wording about how activity is handled. If those details are not clear on the screen, that is a reason to pause rather than assume the best.
That careful approach is one of the most useful ways to use Ava. Instead of treating it as a magic button, I would use it as a structured checkpoint before making a credit-related decision. The app can be valuable even when the most important action is deciding not to proceed with an option that does not fit your budget.
A realistic routine for using it
Imagine someone who has recently moved, has little established credit, and wants to prepare for a future apartment application. They download Ava after work, review the onboarding questions, and choose an approach that they can maintain without straining their monthly cash flow. Rather than checking obsessively, they set one regular moment each week to review the account, confirm that expected payments are manageable, and keep their broader budget up to date.
That routine is more realistic than expecting the app to solve everything in one session. The user still needs to keep enough money available, avoid taking on obligations merely to chase a score, and monitor other accounts separately. Ava can serve as the credit-focused part of the routine, while a bank app or spreadsheet handles rent, utilities, groceries, and savings. In that setup, the app has a clear job instead of becoming another cluttered financial screen.
A second useful scenario is someone who has been rejected for a conventional credit card and wants a less intimidating starting point. Ava may feel more approachable because its purpose is explicit. However, I would compare the available terms with other legitimate credit-building routes before accepting anything. A familiar alternative may be better if it offers clearer reporting information, lower overall costs, or a product that matches the user’s existing banking relationship.
Where the app can save mental effort
The strongest practical benefit is organization. Credit improvement involves small decisions that are easy to forget: knowing what you accepted, remembering when money must be available, and checking whether a product still makes sense as your circumstances change. A dedicated credit app gives those tasks a home. I find that more useful than vague advice such as “pay bills on time,” because it encourages a person to connect the advice with a repeatable routine.
Another non-obvious benefit is psychological clarity. People with damaged or limited credit often avoid the subject because every reminder feels discouraging. A focused app can make the problem feel more concrete: review the next action, understand the obligation, and decide whether it is affordable. That does not improve a score by itself, but reducing avoidance can improve the consistency that credit building requires.
I would also use the app as a comparison trigger. Before accepting an offer, I would write down what I expect to gain, what I must pay or repay, and what could happen if my income changes. This turns the app from a passive recommendation engine into one step in a personal decision process. The best result may be proceeding, waiting, or choosing a different route.
The tradeoffs that deserve attention
The first limitation is that a credit-building app cannot control every factor affecting a credit profile. Existing debt, missed payments, account age, utilization, and information from other accounts can all matter. Someone who needs help with debt repayment, fraud, inaccurate reports, or a complex financial dispute may need a different service or professional guidance. Ava is not the right single tool for every credit problem.
The second limitation is the tension between speed and patience. A user may install the app expecting a quick visible transformation and become disappointed when progress takes longer. I would judge it by whether it helps me make sustainable decisions, not by a promise implied by a short slogan. If you cannot comfortably meet an obligation, the potential credit benefit is not worth putting essential expenses at risk.
There is also a learning curve hidden beneath the simple idea of “building credit.” New users may not immediately understand the difference between an account being opened, activity being reported, and a score changing. Those are not interchangeable events. I would take notes during setup and save the important terms for later reference. If you are helping a teenager or another first-time user, go through the details together instead of handing over the phone and assuming the app explains everything.
Privacy and trust are additional considerations for any finance app. I would install it only from an official app store, use a strong device lock, and avoid entering sensitive information while connected to an untrusted network. I would also review the app’s permissions and privacy explanations in the store or inside the product. These are not reasons to reject Ava automatically; they are sensible precautions whenever an app is connected to financial decisions.
How it compares with familiar alternatives
Ava occupies a different space from a normal bank app. A bank app is usually best for checking balances, moving money, and reviewing transactions. It may be the place where you confirm that funds are available, but it is not necessarily designed to guide a dedicated credit-building plan. I would use both if needed: the bank app for cash flow and Ava for the credit-focused workflow.
It also differs from a standard secured credit card. A secured card can be useful for someone who wants a conventional card experience and understands how to keep utilization low and payments on time. Ava may be more appealing to a person who wants a guided alternative, but the better choice depends on the exact terms, reporting arrangement, and spending habits involved. If you already manage a secured card responsibly, adding another product could create needless complexity.
Credit-monitoring services are another comparison point. They can help you watch reports or scores, but monitoring is not the same as building credit. Ava’s appeal is the action-oriented side: it is intended to help a user participate in a credit-building process rather than merely observe a number. On the other hand, someone mainly worried about identity theft or errors may get more value from a service dedicated to alerts, report access, and dispute support.
Finally, nonprofit credit counseling can be a better option for a person facing serious debt or repeated missed payments. An app is convenient and private, but convenience cannot replace a tailored conversation about creditors, repayment priorities, and household affordability. I would choose Ava for a focused, manageable starting point and seek counseling when the underlying problem is larger than credit history alone.
Who is most likely to benefit
I see the clearest fit for adults who are new to credit, rebuilding after setbacks, or looking for a more organized way to think about credit-related actions. It can also suit someone who prefers handling routine financial tasks on a phone and is willing to read carefully before accepting an offer. The Everyone age rating makes the app broadly accessible, but broad accessibility should not be mistaken for suitability for every financial situation.
The app is less suitable for a person who wants a guaranteed score increase, needs immediate borrowing for an emergency, or cannot reliably reserve money for a new obligation. It is also a poor fit for someone who already has a well-managed credit strategy and would gain nothing from adding another account or workflow. In that case, a simple calendar reminder and existing bank tools may be enough.
Before starting, I would ask myself three questions. Can I explain what I am signing up for in plain language? Can I meet the related payment or account responsibilities even during a difficult month? And do I have a specific goal, such as establishing history or preparing for a future application, rather than a vague hope that my score will rise? If the answer to any of these is no, I would wait and learn more first.
My verdict after weighing the value
Ava Finance is worth considering because the download is free, the purpose is clear, and the app gives credit-building a more approachable place in a person’s daily money routine. Its strongest value is not a mysterious shortcut; it is the combination of accessibility, focus, and structure. For a careful user, that can make an intimidating subject easier to face and easier to manage.
My recommendation comes with an important condition: treat every financial choice inside the app as a real commitment, not as a harmless app feature. Read the terms, compare alternatives, protect your information, and never sacrifice rent, food, utilities, or emergency savings for the possibility of improving credit. If you want a focused starting point and can keep the obligations affordable, Ava is a sensible app to explore.
If your main need is debt counseling, detailed budget management, identity protection, or a conventional card with familiar rules, another option may serve you better. For everyone else, I would give it a cautious try rather than an unconditional endorsement. The best value comes from using Ava as a decision aid and routine builder, not as a promise of instant credit repair.
Overall, I think the app earns attention from people who need a clear first step and appreciate a free way to investigate credit building on their phone. Its 4.7 average and substantial user base add confidence that the experience is resonating with many users, while the free listing makes experimentation less intimidating. Just keep expectations grounded: the app can support better decisions, but the durable result still comes from affordable commitments and consistent financial behavior.


